Defined benefit pensions
Exploring your options with your Defined Benefit pension scheme is one of the biggest financial decisions you will make in your lifetime. So we want you to read everything we've provided carefully, including these key points.
Where we start
We know that there will be some aspects of keeping your defined benefit pension that may be attractive to you. There may also be some aspects of transferring the scheme that will be attractive too. For most people, after weighing everything up, they are better off keeping the defined benefit pension as it is. When we provide advice, we always start from the position that it is going to be in your best interests to keep the scheme as it is. There would have to be several good reasons to take us from that starting point.
You cannot change your mind later
It is very important to keep in mind that if you start taking your pension income from the defined benefit scheme, or if you transfer your pension elsewhere, these are irreversible decisions. You cannot decide later to stop your pension income from a defined benefit pension. You also cannot decide later to put your transferred pension fund back into the defined benefit pension. It is vital your advice is thorough and takes all your circumstances into account. It is also essential that you tell your financial planner absolutely everything, and carefully consider everything they advise. We will always provide the advice that we firmly believe is in your best interests, now and for the long-term.
You are not the same as your colleagues
You may know some colleagues or friends who have been given advice about their own defined benefit pensions. Perhaps they have shared with you what the advice and experience was. Whatever that was, it's essential you acknowledge you will not be exactly the same as your colleagues. Your health, family structure, savings, plans for retirement, comfort with financial decisions, debts, what you earn as a family and what you spend... they will all be different. Each of these factors influences our advice. Whatever advice your colleagues might have been given, do not assume that advice will also apply to you.
The biggest numbers are not always the best option
You may have done some rough calculations to work out which option is best for you. However, the option that appears the most generous financially is not always the best fit. It may be less robust, more risky, more complicated or need more maintenance. Your health, family set-up and financial experience all impact on the position.
Feeling anxious or distracted can lead to regrettable decisions
If you are in a situation where you are worried about redundancy, your job security for the future, your health, a relationship breakdown, loss of a loved one or increasing debts, it might be hard to keep focus. Making decisions at these times can be especially hard. It can be difficult to concentrate, take in complicated concepts, or to challenge what you are being told. You are more likely to make a decision you will later regret unless you are given breathing room to make decisions in your own time and without any pressure. If any of these apply to you, seriously consider whether now is the right time to be taking complex and high-consequence advice. If it is unavoidable, make your position clear to your financial planner, so extra time and consideration can be given.
We provide you with advice - we do not take instructions
Taking financial planning advice about your defined benefit pension means that we absorb your financial situation, any concerns right now and your goals for the future, thinking about your career, family, and lifestyle. We assess whether the defined benefit pension will best meet your needs if it is kept as it is, or transferred into a different type of pension arrangement, taking absolutely everything into account, and simulating a range of different scenarios over your lifetime. We provide you with our carefully considered advice. We will always implement that advice, if you are comfortable to go ahead with it. If our advice is to keep your pension, and you disagree with our advice, we will explore why we have a difference of opinion and explain how we have come to our decision. We will provide a statement to confirm you have received our advice, but we will not take your instructions to arrange a transfer or recommend where that money should go.
Timing is important
Your pension scheme is designed to provide you with income and a lump sum when you retire. It is usually appropriate to think about your options up to 2 years before you plan to retire. If you have much longer to go before you'll retire, it's wise to consider why you are looking at your options now. We will not provide anyone with advice about their defined benefit pension schemes when they are under 50 years old, unless they are in a profession with a low retirement age or in extremely ill health.
What's right today isn't always right tomorrow
You will hopefully enjoy a long and healthy retirement when the time comes. Your early years of retirement may look very different to your later years. Your lifestyle, where you live, your health, family and priorities could change significantly. What feels like the best option financially today may have a knock on affect much later down the line and can even mean you needing to make compromises about your goals and lifestyle. Assessing your defined benefit pension means looking for the best outcome now and also for the rest of your life.
Investigate subsidised or free advice services
Some defined benefit pension schemes have a relationship with a financial advice company that can provide you with advice. Often, that advice is wholly or partly subsidised by the scheme's employer, meaning it could be free or very low cost to you. If you are in that position, we recommend fully exploring what is available to you first, before comparing that with offerings from other financial planners like us.
Understand costs
All financial planners will charge a fee for their advice, regardless of the likely outcome. If your scheme does not provide subsidised or free advice from a preferred company, you must pay the advice fees yourself. While fees can be paid from a transferred pension fund, you will not know at the outset whether a transfer will be recommended or not. A defined benefit pension scheme cannot pay any fee if the advice is for it to be retained, unless you then go on to take your retirement benefits from it. Fees could potentially be paid from your savings, investments or surplus income that could be saved within the next three months. You must have the means to pay our fee, regardless of the outcome, without it affecting your standard of living, or going into debt.
If you are in serious financial difficulty this does not preclude you from receiving advice. But we will only engage to give you advice if the only viable options available to you are to start taking your benefits from the pension or to effect a transfer, which would make it possible to pay our fee.
Help from the Personal Finance Society
The Personal Finance Society has a code of practice called the Pension Transfer Gold Standard, which we respect and follow. They have produced a guide to help with your research and decision-making process when choosing a financial planner to give advice about a defined benefit pension. We strongly recommend clicking on the image below to read it.
Help from our regulator, the Financial Conduct Authority
The Financial Conduct Authority have produced a video to help explain the process we must follow when providing you with advice, the information we should provide and the questions we should ask. We strongly recommend you watch this before you engage with us or any other financial planner.
"She listens carefully to what one wants... and even intuits what is unsaid in suggesting options that I was entirely unaware of. She has a friendly manner and does not attempt to impress through parading her knowledge upfront, but that expertise is there should you wish to delve deeper into a particular aspect. I have no hesitation in recommending her." Keith, Nottingham
Defined benefit pensions
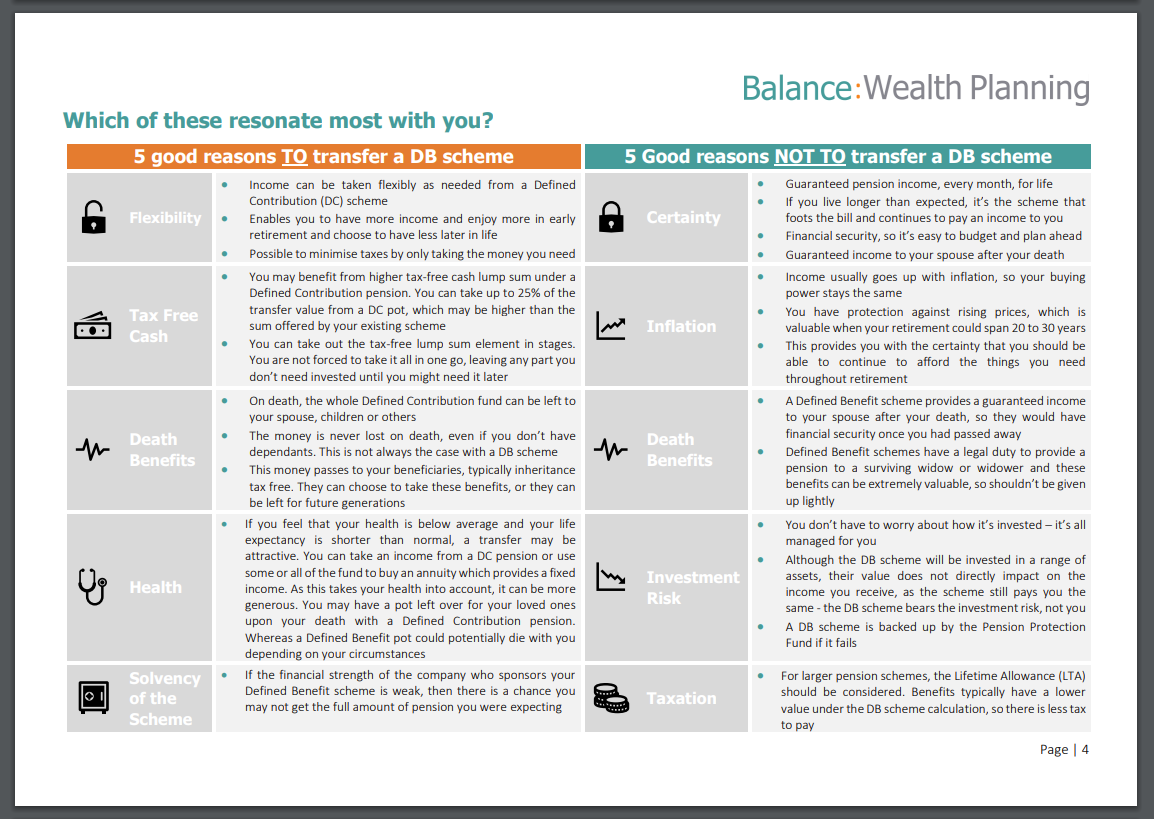
Advantages and disadvantages of a Defined Benefit pension scheme
Before you decide whether to ask us to give you advice, it is helpful to make sure you understand the general advantages and disadvantages of a defined benefit pension scheme, and what the difference could be if you transfer to a personal pension or annuity. Transferring is not right for everyone. In fact, the majority of people are best advised to keep their scheme benefits as they are. You may even find that you decide you want to keep the scheme as it is and don't need any advice from us at all.
This is a very complex area of advice and your decision cannot be undone later.
We have produced an essential guide to the key considerations which you can download here.
What outcomes to expect
If you take advice from us, we will give you one of two outcomes.
1. We can show you that the transfer is clearly in your best interests and suitable for you.
2. We cannot show that the transfer is in your best interests so we believe that remaining in your current scheme is suitable for you.
Abridged advice
Some financial planning companies offer abridged advice. This comprises a shorter, simplified, assessment of your circumstances, which carries a lower cost. The outcome of abridged advice will be:
1. We cannot rule out the possibility that a transfer would be in your best interests and suitable for you. We recommend you take full advice about transferring your defined benefit pension.
2. We cannot show that the transfer is in your best interests so we believe that remaining in your current scheme is suitable for you.
We do not offer this service, because we believe the full advice process is safer for you.
The scope of our holistic financial planning advice
Assessment of your defined benefit pension scheme will form part of your wider holistic financial plan, and include the following:
- Full details of the scheme's benefits and options
- Assessment of whether the scheme's benefits are the best fit for your needs, or if you would be better placed taking the transfer value available and looking at alternatives. These are the most common alternatives:
- A personal pension (including a workplace pension or a Self Invested Personal Pension)
- An annuity (which could include an annuity for a fixed term or for the whole of your life)
- Consideration of which of these options is most appropriate for you right now:
- A full transfer to an alternative type of pension or annuity
- A partial transfer to an alternative type of pension or annuity
- Start taking your benefits from the current pension straight away
- Do nothing for now and keep the scheme benefits as they are
If you are an active member
If you are actively accruing benefits within a defined benefit pension scheme, we will give you advice about whether it's in your best interests to continue or to opt-out as part of our work for you. We will do this by default and there is an extra cost that applies. If you have already made a decision to opt-out of further benefit accrual in the scheme, and have told them that, you can ask us not to give you that advice, should you wish. We will then treat you as a deferred member of the scheme.
Costs of advice
Our advice fees are the same, regardless of what we recommend, even if our advice is to keep the scheme as it is.
Our initial consultation meetings are free of charge. We will provide you with a quotation for our advice, which will be based partly on the pension scheme's transfer value, and partly on the complexity of your general financial situation. It will always be a flat monetary fee, not a percentage of any value and there is no charge until you engage with us.
"She listens carefully to what one wants... and even intuits what is unsaid in suggesting options that I was entirely unaware of. She has a friendly manner and does not attempt to impress through parading her knowledge upfront, but that expertise is there should you wish to delve deeper into a particular aspect. I have no hesitation in recommending her." Keith, Nottingham
Your key contacts
Working with us means you will have a team of experts looking after you. Our handpicked team are highly qualified and professional. Most importantly, they're all passionate about helping you.
The combined expertise and drive of our multi-skilled and award-winning team have been the secret to our success from the beginning, and that continues to this day.
We understand that you'll want to do some background checking and research before we start working together. Please browse our website to see our expert team. For each of our Financial Planners you'll see a Research Pack on their profile pages, with more information about their qualifications, background and expertise.
Get in touch
0800 7723456 | team@balancewealth.uk | www.balancewealth.uk
The Point, Loughborough Road, West Bridgford, Nottingham NG2 7QW