Introduction
The purpose of this document is to explain who we are, what we do, and how we charge. It is not specific to you and your situation, but it is still important. If there is something you don’t understand please ask us to explain it.
You can navigate through the different sections by clicking the left hand menu.
If you hover over the bottom of the screen you can also click to save the whole document as a PDF, or to print it.
This document is updated regularly. The last update was on 7th May 2026.
Questions
If you have a question about any aspect of our services, please contact us using any of these methods.
Balance: Wealth Planning Limited
The Point, Loughborough Road
West Bridgford
Nottingham
NG2 7QW
T: 0800 7723456 | F: 0872 1117721 | team@balancewealth.uk | www.balancewealth.uk
Financial Planning - what to expect
We provide our clients with a clear and focused financial planning service. It has been carefully designed to help you identify what you want to achieve, then to arrange your finances to put you in the best possible position to succeed.
Discovery stage
Before committing to anything, we want to be sure we share the same principles and are ready to work together for the long term. It is important you work with a financial planner you like and trust.
We will get to know each other through an exploratory meeting, free of charge. We will ask questions to help understand what is important to you and what you want to achieve in your life, in the short and long term. We will also ask about your financial situation. Once we have an understanding what precise work you’ll require, we provide a tailored quote to reflect this. There is no charge until you engage with us.
Advice stage
After you have engaged with us, we will carefully consider your situation and what you want to achieve. We will then clearly set out our advice to you in a report. This will include an action plan of what to do. Depending on your circumstances, our advice might include details about restructuring your wealth, updating your investments, tax planning, reducing costs and improving your options.
Action and implementation stage
When you are ready, we will work with you to start making the changes we recommended. We will do as much as possible for you.
Review stage
Your situation will change over time and it is important that your financial plan is regularly adjusted. We usually review your plan and meet you at least once a year, based on what you would prefer.
We will be in touch from time to time throughout the year. You should contact us if there is ever anything we can help with or any concerns. We offer meetings face to face or via online video calls, and all contact is included in our ongoing service.
Our advice
Understanding your situation
In order that you can receive the best financial planning advice, it is important to allow us to understand your whole situation, giving us accurate and up to date information about your circumstances and objectives when we request it. If you don’t want to discuss or receive advice about a particular area of financial planning, you can ask us to exclude it from our considerations, although that can have a bearing on the advice we might otherwise have given.
How you will receive our advice
Our financial planning advice will always be in writing in a letter or report, and we will set out details of any special risks that may be associated with the products or investment strategies we have recommended. This might be sent to you in paper form, by email or as an internet link. You should read these documents and ask us any questions before you make any decisions.
We will usually arrange to go through our advice with you together, so we can discuss our recommendations, identify obstacles or concerns and help you decide what to do next. As part of this discussion we may decide to think about alternatives to the advice originally suggested. If that’s the case, we will revisit our advice and send you a revised financial planning report.
Legal and accounting advice
We are not qualified to provide legal or accounting advice or to prepare any legal or accounting documents. This means that it’s your responsibility to refer any legal or accounting matter to a suitable specialist in that field. We can usually recommend someone to help you.
Financial products
We offer independent financial planning advice, and as part of that we may recommend financial products. We consider a wide range of financial strategies and products for our clients and are constantly reviewing the market to ensure that the services and products we offer are appropriate.
Advice about financial products
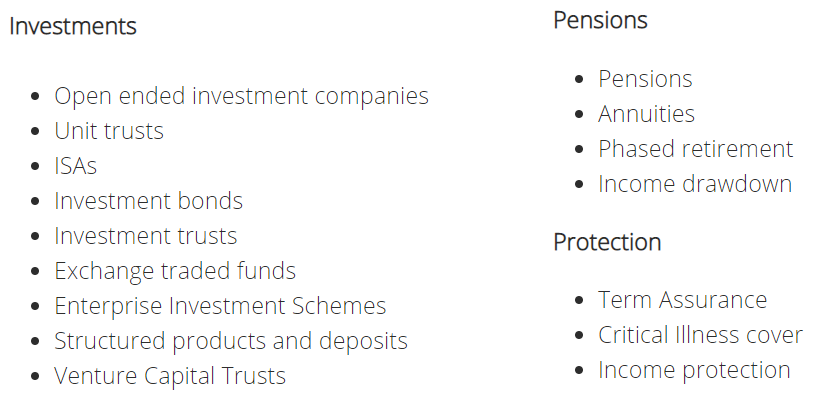
Before we recommend any financial product, we will consider your personal circumstances, your financial goals, the services you need, the cost of investing, how much risk you are prepared to accept in an investment product and how much of a drop in its value you could withstand. We will ensure what we recommend is suitable for you. The financial products we can advise on are:
The Personal Finance Society (PFS) has granted us their Pension Transfer Gold Standard, which is awarded to financial planning companies that adopt and champion a strong ethical code of conduct for pension transfer advice. Here's what you can expect from financial advisers who have adopted the Pension Transfer Gold Standard.
We don’t provide advice in relation to individual share holdings, options, futures and other derivative contracts. If this is something you need assistance with, we can refer you to a stockbroker. When we provide protection, or contingency planning services we will act as an insurance intermediary and will provide advice which is based on a fair and personal analysis of the market.
Cancelling financial products
Full details of any financial products we recommend to you will be provided in the relevant product information you will receive. This will include information about any product cancellation rights along with any other early termination rights and penalties.
Investments
Advice about investments
We may agree to provide you with an ongoing service that includes reviewing any investments we recommended, to make sure they are still suitable for you. We will usually carry out this review at least annually unless we agree otherwise. As part of our ongoing service and planning review we will make contact to check whether the information we hold about you is still accurate and up to date.
We will tell you in writing whether we feel the investments are still suitable for you and, if relevant, we will give you our recommendations for any changes.
Discretionary fund management
We may recommend holding some or all your investments with a discretionary fund manager (also known as a DFM or a discretionary investment manager). A discretionary fund manager is a professional investment management company who would be appointed to monitor your portfolio and make investment decisions on your behalf. If we recommend a discretionary fund manager, we will explain to you what their role and responsibilities are.
Sometimes we may need to act as your ‘agent’ in relation to the part of your portfolio held with a discretionary fund manager. This means that you won’t have a direct contractual relationship with them and instead the discretionary fund manager (DFM) will treat our firm as its client. Before setting up this type of arrangement we will explain the implications to you, which can include a loss of the right to cancel the discretionary portfolio, as well as altering the process in the event of a complaint about your investment. In this instance you would not have the right to escalate your complaint to the Financial Ombudsman if you were unhappy with the resolution provided by the DFM.
Investment liquidity
We may occasionally recommend investments that may not be possible to sell easily or quickly. We will only do this where appropriate but, if we do, we’ll draw your attention to the risks associated with the investments in our detailed advice report.
Investment risks
Please be aware that investments can fall, as well as rise, and that you may not get back the full amount invested. The price of investments we may recommend may depend on fluctuations in the financial markets, or other economic factors, which are outside our control. Past performance is not necessarily a guide to future performance.
Specific warnings relevant to the investments, investment strategies or other products we arrange are set out in the relevant product literature which will be provided at the time of our recommendation.
Defined benefit pensions
Our default assumptions
If you have a defined benefit pension scheme, our default assumption will be that you will continue to be either an active or deferred member of that scheme and will take the benefits at the normal retirement age.
We will only give you advice about the transfer, opt out or conversion of your benefits in a Defined Benefit pension scheme if you specifically ask for it and agree our additional service terms.
Defined benefit pension transfers
If you take advice from us about whether to transfer your defined benefit pension, we will give you one of two outcomes:
1. We can show you that the transfer is clearly in your best interests and suitable for you.
2. We cannot show that the transfer is in your best interests so we believe that remaining in your current scheme is suitable for you.
Abridged advice
Some financial planning companies offer abridged advice about whether to transfer your defined benefit pension. This comprises a shorter, simplified, assessment of your circumstances, which carries a lower cost.
The outcome of abridged advice will be:
1. We cannot rule out the possibility that a transfer would be in your best interests and suitable for you. We recommend you take full advice about transferring your defined benefit pension.
2. We cannot show that the transfer is in your best interests so we believe that remaining in your current scheme is suitable for you.
We do not offer this service, because we believe the full advice process is safer for you.
Defined benefit pension transfers for active members
If you are an active member of a Defined Benefit pension scheme and request our advice about the transfer or conversion of your benefits, we will automatically include advice about opting out as part of that process.
If you have already made your decision about opting out and do not want our advice about whether that is the best course of action, you can confirm that to us in writing, and we will treat you as a deferred member.
Extra guidance
We have a suite of separate guidance about defined benefit pension transfers, which you can access online here.
Service agreement
If you ask us for financial planning advice and explain what you need, we will give you a written proposal. That proposal will set out what we can do to help you and what the cost will be. We may give you more than one service level to choose from.
If you accept our proposal, we both agree to the terms of a Service Agreement, which commits us to provide the services it describes, and for you to pay our fees, which are expressed in pounds and pence. If we make a change to the scope of our service or the associated costs, that will be covered in a Supplemental Service Agreement.
We will never carry out any services that will incur a cost without a Service Agreement in place that has been accepted by all parties.
We will treat a Service Agreement as being accepted if it is signed and returned to us, or if you email us to confirm that you accept it. Our service will start from the date of the Service Agreement between us.
During the course of an ongoing relationship we may agree to provide additional services which may incur a one-off fee. In particular, additional fees can apply if you do not receive our standard service with a fixed, inclusive, monthly fee.
Where an additional fee arises from giving advice about an investment transaction, we will set out the proposed fee in an electronic transaction approval form. Submission of that form will be taken as your acceptance of the fee and agreement for it to be deducted from the investment it relates to.
Where an additional fee arises from proposing an additional service that does not relate to an investment transaction, we will ask you to sign a Supplemental Service Agreement or similar document before we start.
How we charge
How we are paid
We normally charge fixed fees for our financial planning services.
Initial fees, and additional one-off fees, can be paid by cheque or transfer from your bank account or can often be taken directly from a pension or investment portfolio.
Ongoing fees can be paid by standing order from your bank account or taken directly from a pension or investment portfolio.
Where we are paid by deduction from a pension or investment, this will reduce the amount you have left to invest, it can mean that money is kept in cash for that purpose when it could have been invested, and may have other consequences, depending on your circumstances. We will explain these options and recommend the most suitable for you.
We cannot accept payments by cash, credit card or debit card.
If you invest in one of our in-house investment portfolios, we charge 0.2% of the value as a portfolio management charge. This charge applies to all investors in those portfolios and pays for its ongoing maintenance and review. We do not charge this if we recommend a portfolio from another manager. However, they may have their own charge that applies instead.
Commission
We will not ever be paid a commission for a new investment or pension plan we arrange.
We will usually receive commission for arranging insurance policies. However, we will give you the option of paying a fee if we think it will suit you better than any alternative and tell you how much it is. If the commission is less than our quoted fee, or if you cancel the policy and we have to return commission to the insurance company, we may ask you to pay the difference.
If you have plans that you appoint us to manage but were arranged by another adviser, these may be set up to pay commission on an ongoing basis. If it is possible to stop that commission and to use it to enhance your investment or reduce your premiums paid, we will do so.
If that is not possible, we will retain the commission, put it towards our annual fee and will tell you how much it comes to every year. If it is higher than our annual fee, we will refund you the difference.
Fee shares
If we recommend a cash management platform that we partner with, they may pay us a share of the fee they charge you. This is typically around 0.1% of the cash balance. This will impact the interest you receive from the bank accounts they place your cash savings into.
How we calculate our fees
We usually calculate our proposed fees based on the complexity of your circumstances, the scope of the advice proposed, and the anticipated time cost of providing you with the service you need on an initial and ongoing basis. In estimating the time costs, we refer to our hourly charges, which are:
- Financial planning: £330
- Research and technical support: £176
- Administrative Support: £133
We do not categorise our clients or offer ‘off the shelf’ services. Instead, the scope of advice can be tailored to suit - ranging from a light-touch to a more intensive service.
In some circumstances we will charge an initial fee that reflects the risk or complexity of the advice required. This includes providing advice about defined benefit pension transfer or opt outs. We will occasionally agree a different charging basis for ongoing services, such as a time costed fee in arrears, or a percentage of assets under advice. We typically will only do that when providing advice about Defined Benefit pensions or to provide consistency for clients moving to us from another adviser.
Initial meetings and discussions that we have before the Service Agreement is signed are free of charge.
We increase our fixed ongoing fees with effect from 1st September every year. The fee is increased by the greater of the rate of inflation as measured in July every year, or 5.5% if higher.
When our fees are due
Our initial fees become due when our financial report has been received by you. Where you intend to pay by cheque or bank transfer, we ask for payment within 30 days.
Where you intend to pay out of transferred investment or pension funds, we appreciate that does not always happen quickly and will generally wait until the transfer has taken place to collect our fee through that method. If after 60 days it has not been possible to collect our fee through your pension or investment as intended, we will request that you settle the fee personally.
If our fees are not paid when they fall due, we have the right to suspend our services and to retain any of your documents until the fee has been paid. If we incur costs in pursuing any outstanding fee, we also reserve the right to recover those from you. We may also charge interest on overdue amounts, including expenses and VAT, from the due date until payment is received in full. For personal clients, we will charge 3% above the Bank of England base rate.
Managing the cost
When you engage with us to provide financial planning advice, it is your responsibility to make sure you have the means to pay our fee at the outset, regardless of what the outcome of our advice might be for you, without it affecting your standard of living, or going into debt.
For advice about transferring out of a defined benefit pension scheme, all financial planners will charge a fee, regardless of the likely outcome. You must expect to have the means to pay our fee, regardless of the outcome, when you engage with us.
If your scheme does not provide subsidised or free advice from a preferred company, you must pay the advice fees yourself. While fees can be paid from a transferred pension fund, you will not know at the outset whether a transfer will be recommended or not. A defined benefit pension scheme cannot pay any fee if the advice is for it to be retained, unless you then go on to take your retirement benefits from it. Fees could then potentially be paid from your savings, investments or surplus income that could be saved within the next three months.
If you are in a position where it is essential you take financial advice and you do not have the means to pay at outset, we may agree for your fees to be paid over a period of time, not exceeding 12 months. Interest will not be charged. This is agreed at our discretion and as an exception only where circumstances leave no other sensible option.
What our services include
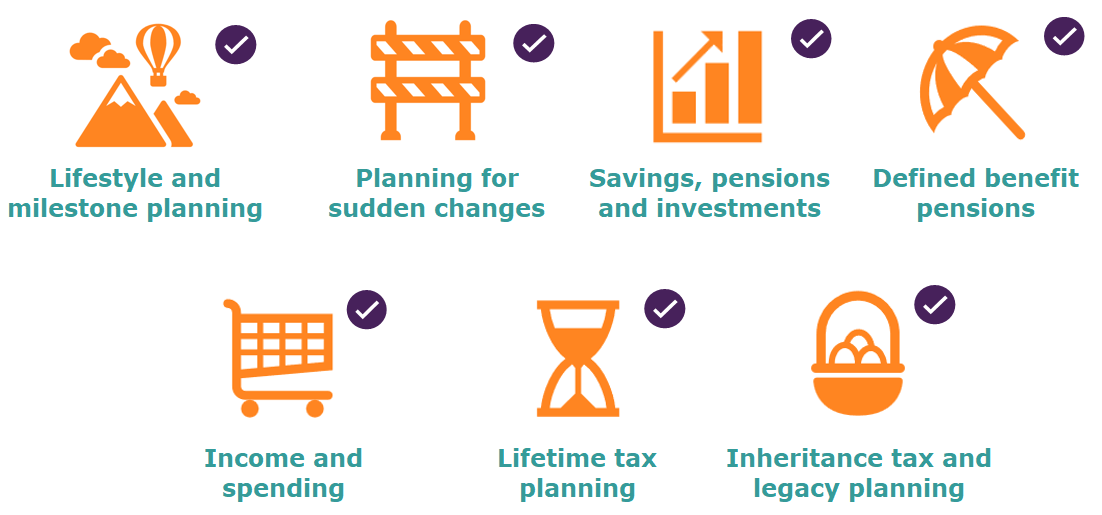
7 Pillars of Financial Planning
These are our 7 Pillars of Financial Planning. Each one brings stability and structure to a Financial Plan.
Initial service
Our initial service will focus on one or more Financial Planning pillars.
For clients receiving advice about all the Financial Planning pillars:
If all pillars are included, our service would typically comprise:
- Help you identify what you want to achieve, in the short and long term.
- Carry out a comprehensive analysis of your existing finances, including all your savings, pensions, investments, personal protection and tax planning arrangements.
- Forecast your wealth over your lifetime to identify issues over the long term.
- Stress-test your situation, looking at scenarios such as serious illness, death, loss of income and poor investment performance.
- Present our recommendations and draft action plan to you, identify any obstacles, and discuss them with you. We will make revisions as needed, until we are all agreed.
- Provide a clear and detailed recommendation report with an action plan to follow.
When you are ready to start putting the recommendations into action, we will do as much of that as we can on your behalf and will help you with your own actions as far as possible, unless we agree otherwise. We will:
- Liaise with your other professional advisers as required.
- Help you complete any paperwork and submit it to third parties as required.
- Follow everything through to completion and keep you up to date with our progress.
For clients receiving advice only about the Lifestyle & Milestone Planning pillar:
- Help you identify what you want to achieve, in the short and long term.
- Collect details of your existing finances, including all your savings, pensions, investments, personal protection.
- Forecast and stress-test your wealth over your lifetime to identify issues over the long term.
For clients receiving advice about a select number of Financial Planning pillars:
If a select number of pillars are included, our service would typically comprise these elements as a minimum:
- Help you identify what you want to achieve, in the short and long term.
- Present our recommendations and draft action plan to you, identify any obstacles, and discuss them with you. We will make revisions as needed, until we are all agreed.
- Provide a clear and detailed recommendation report with an action plan to follow.
The remaining service and advice will be dependent on the pillars that have been included.
Ongoing service
Our ongoing service is not compulsory.
For clients receiving advice about all the Financial Planning pillars:
Our ongoing service will focus on one or more Financial Planning pillars. If all pillars are included, our service would typically comprise:
- Meet with you at least annually with the aim of helping you to achieve the personal objectives you have set.
- Review your long-term financial plan with you at least every year, including updating your goals and objectives.
- Regularly identify where you might want to make changes to your financial plan.
- Make use of ongoing tax planning opportunities.
- Recommend changes to your savings and investment strategy where required.
- Assess your investment performance against the targeted rate of return.
- Ensure your portfolio is rebalanced and maintained as required to ensure it remains appropriate.
- Let you know about any changes in legislation that may affect you.
- Be on hand for all calls, discussions, and correspondence to update each other on any changes or to ask questions.
- Review your contingency plans and recommend changes as needed.
- Stay in touch with updates, news and invitations that may interest you.
- Maintain our records.
- Liaise with your other professional advisers as needed.
Between our regular reviews, you have unlimited access to our advice and support on any financial issues at all. All questions are welcome, and we like to keep in regular contact with you.
For clients receiving advice only about the Lifestyle & Milestone Planning pillar:
This service is designed to focus on cash flow and lifestyle planning, and it does not include any advice about the other Financial Planning pillars. An ongoing service focused on this pillar typically includes the following:
- Meet with you annually with the aim of helping you to achieve the personal objectives you have set.
- Review your cash flow forecasts with you at least every year, including updating your goals and objectives.
- Let you know about any changes in legislation that may affect you.
- Be on hand for all calls, discussions, and correspondence to update each other on any changes or to ask questions.
- Stay in touch with updates, news and invitations that may interest you.
- Maintain our records.
Between our regular reviews, you have unlimited access to our support on any financial issues at all. All questions are welcome, and we like to keep in regular contact with you.
If you need any advice that falls into a Financial Planning pillar that is not included in your service package, additional fees will apply. We will let you know if that applies and recommend extending our service to include that pillar of advice.
For clients receiving advice about a select number of Financial Planning pillars:
If a select number of pillars are included, our service would typically comprise these elements as a minimum:
- Meet with you annually with the aim of helping you to achieve the personal objectives you have set.
- Let you know about any changes in legislation that may affect you.
- Be on hand for all calls, discussions, and correspondence to update each other on any changes or to ask questions.
- Stay in touch with updates, news and invitations that may interest you.
- Maintain our records.
The remaining service and advice will be dependent on the pillars that have been included.
Between our regular reviews, you have unlimited access to our support on any financial issues at all. All questions are welcome, and we like to keep in regular contact with you.
If you need any advice that falls into a Financial Planning pillar that is not included in your service package, additional fees will apply. We will let you know if that applies and recommend extending our service to include that pillar of advice.
What the service costs
Initial service fee
We will charge an initial fee for our initial service, irrespective of whether any financial products have been recommended.
Because we typically work on a holistic basis, and each person’s circumstances and requirements can differ greatly, the cost can vary widely too. Fees typically range between £4,970 - £13,780 for our Full Service, where advice about all Financial Planning pillars is included. However, our fees can exceed this for clients with more complex or bespoke needs and circumstances, typically found with invested wealth levels approaching or exceeding £10,000,000. This fee includes carrying out all the actions recommended.
Initial fees for advice focused on just one Financial Planning pillar starts at £2,770. Advice in other Financial Planning pillar areas can be added to fit what you need.
Ongoing service fee
We charge a fixed monthly fee to provide ongoing services where they are required. The depth of ongoing service can vary greatly, so our fees reflect that. Fees typically range between £414 - £1,148 per month for our Full Service, where all advice is included. However, our fees can exceed this for clients with more complex or bespoke needs and circumstances, typically found with invested wealth levels approaching or exceeding £10,000,000.
We do not typically charge extra fees for clients receiving our Full Service unless there are exceptional circumstances or if we are providing Defined Benefit pension transfer assessment advice.
A service focused on one Financial Planning pillar typically starts at £160 per month. Additional fees apply for extra services, meetings, advice or events during the year.
Investment management fee
If we recommend you invest in one of our in-house portfolios, we will deduct a Portfolio Management Charge of 0.2% a year from the value of the amount invested. This is collected on a monthly basis.
Overall costs
Before we provide you with our advice about any investments, we will add together all the costs and charges payable so that you are able to understand the overall costs of our services and recommendations. This is referred to as aggregated costs and charges information.
Other costs and charges
Depending on the services we provide, there may be costs and charges (including taxes), not charged by us, but related to the financial products we arrange for you. These charges may be one-off (payable up front) or payable on an ongoing basis. For example:
- Service costs: If your investments are held on a wrap platform (an online investment administration service) or managed by a discretionary fund manager, they may make a charge for their services.
- Investment costs: These are the costs relating to the manufacturing and managing of your investments – for example, fees charged by the investment fund manager, costs relating to investment transactions.
- We will always disclose any third-party costs as part of making our recommendations.
- Part of our fees may, in the future, be subject to VAT.
Execution Only instructions
Full Service examples
Anne and Ben have two pension plans between them that they want to review, a stocks and shares ISA each that Ben has been managing himself, and they want to invest an extra sum from their savings. They need to put in place some more personal insurances. They are some way off retirement and are at a stage where they want to focus on accumulating wealth for the future, repaying debt and having a good work/life balance. They want to meet once a year for a full planning review. Their total investments and pensions managed by us will total £500,000.
We recommend a Full Service.
- Initial fee - £4,970 (equivalent to 0.99% of their invested wealth)
- Ongoing fee - £414 per month (£4,970 a year) (equivalent to 0.99% a year of their invested wealth)
*****
Charlie and David are both planning retirement next year. They have four pension plans between them and three investment pots, including ISAs and an investment bond. They want to get everything into good shape so it’s as simple as possible in retirement and they don’t pay any more tax than necessary. They have a small inheritance tax issue and want to make sure that doesn't become a problem later in life. They want to meet once a year for a full planning review. Their total investments and pensions will total £750,000.
We recommend a Full Service.
- Initial fee - £7,150 (equivalent to 0.95% of their invested wealth)
- Ongoing fee - £596 per month (£7,150 a year) (equivalent to 0.95% of their invested wealth)
*****
Ajay and Pari have two pension plans each, a stocks and shares ISA each, and a lot of cash. They run their own business through a limited company. Pari is close to the pensions lifetime allowance and they are both working towards retirement. They want to explore moving their business property into their pension, as well as minimising taxes now and creating a strategy for selling their business in the next five years. They need to understand their inheritance tax position and how to use tax reliefs to their advantage. They want to meet once a year for a full planning review. Their total investments and pensions will total £1,000,000.
We recommend a Full Service.
- Initial fee - £9,430 (equivalent to 0.94% of their invested wealth)
- Ongoing fee - £786 per month (£9,430 a year) (equivalent to 0.94% a year of their invested wealth)
*****
Sonja has several investments, and over £1,000,000 in savings. She is due to receive another £2,000,000 as a pension share settlement. She is self employed and can easily earn £250,000 a year on average. She needs advice about managing income taxes using specialist investment options. She is also concerned about inheritance tax planning. She wants to meet at least twice a year to review her plans. Her total investments and pensions will total £1,500,000.
We recommend a Full Service.
- Initial fee - £11,600 (equivalent to 0.77% of her invested wealth)
- Ongoing fee - £967 per month (£11,600 a year) (equivalent to 0.77% a year of her invested wealth)
*****
Karen and Martin have two pension plans each, and some old portfolios of stocks and shares. They run their own business through a limited company and are just about to sell it for £3,000,000. Sonja has exceeded the pensions lifetime allowance and they are both working towards retirement. They want to prepare for the business sale, in particular managing taxes and understanding what to do with the proceeds. They have a substantial estate including several properties that will be subject to inheritance tax on death so they need a strategy of managing that through a programme of gifts to their children and short term insurances, among other things. They want to meet twice a year for a full planning review. Their total investments and pensions managed by us will total £3,000,000.
We recommend a Full Service.
- Initial fee - £13,780 (equivalent to 0.46% of their invested wealth)
- Ongoing fee - £1,148 per month (£13,780 a year) (equivalent to 0.46% a year of their invested wealth)
*****
Greta is a serial entrepreneur, with a chain of hotels to her name. Juggling her business interests with family trips away means she needs to delegate to trusted professionals. She has investment businesses and trusts in place, as well as investment portfolios. Her focus is on keeping on top of her finances, minimising taxes and keep liquidity so she can change her plans at any time. The total investments and pensions managed by us come to £10,000,000.
We recommend a Full Service.
- Initial fee - £20,720 (equivalent to 0.2% of her invested wealth)
- Ongoing fee - £1,727 per month (£20,720 a year) (equivalent to 0.2% a year of her invested wealth)
*****
Andy and Lisa were fortunate enough to have a big win on the National Lottery, receiving enough to change their own lives completely, and those of their families. Their focus is on investing their winnings wisely and managing the trusts they've put in place, including those to benefit their local community. They need regular support and advice about the decisions they make. They need a financial planner who can act as a co-ordinator between their other professional advisers including their lawyer. The total investments and pensions managed by us come to £20,000,000.
We recommend a Full Service.
- Initial fee - £31,080 (equivalent to 0.15% of their invested wealth)
- Ongoing fee - £2,590 per month (£31,080 a year) (equivalent to 0.15% a year of their invested wealth)
Lifestyle & Milestone Planning example
Jenny is in her 40s with a successful career. The amount she's saved is starting to build up and she is now earning over £100,000. She needs help checking whether she should be saving more, and whether that should go into her workplace pension, or a separate ISA. Her pensions and ISA come to £160,000.
We recommend a package focused on the Lifestyle & Milestone planning pillar.
- Initial fee for a financial plan without any regulated product advice - £2,770 (equivalent to 1.7% of her invested wealth)
- Ongoing fee for a regular review without any regulated product advice - £160 per month (£1,920 a year) (equivalent to 1.2% of her invested wealth)
Focused Advice Package example
Graham is 70 and has been retired for 15 years. Most of his income is from his state pension and defined benefit pensions. He takes £500 pm out of his pension plan as a drawdown sum for holidays and treats. It's unlikely he'll need access to his investments and pensions other than this, unless his health changes and he starts to need care. With no close family or children, legacy planning isn't a priority. His pensions and investments total £300,000.
We recommend a Focused Advice Package which includes advice in some of the Financial Planning pillar areas, but not all. Specifically we include a full review of his pensions and investments at outset and every year, plus a review of his drawdown income.
- Initial fee - £3,790 (equivalent to 1.3% of his invested wealth)
- Ongoing fee - £315 per month (£3,780 a year) (equivalent to 1.3% of his invested wealth)
Your protection
Our regulatory status
We are authorised and regulated by the Financial Conduct Authority (FCA) under reference 629329. We are permitted by the Financial Conduct Authority to advise on and arrange pensions, savings and investment products and non-investment insurance contracts. You can check our details and the areas in which we are permitted to give advice on their register: https://www.fca.org.uk/consumers/fca-firm-checker
Or by contacting them on 0800 1116768. You can also write to the FCA at 25 The North Colonnade, Canary Wharf, London E14 5HS.
Unless we tell you otherwise, we will treat you as what the FCA define as a ‘retail client’. This means that you have the highest level of protection under the regulatory system and should have the right to take a complaint to the Financial Ombudsman Service (FOS).
If we act on your behalf as your ‘agent’ in relation to the part of your portfolio held with a discretionary fund manager (DFM), as explained previously, we, Balance: Wealth Planning, will be treated as the client. This means you can complain to the DFM directly, however you will not be able to escalate your complaint to the FOS if you are unhappy with the resolution offered by the DFM. Please note, this is only in respect of the investment portfolio itself.
The FCA regulates the financial services industry in the UK but does not regulate all financial products. It also does not regulate tax advice. Most of the products we recommend are regulated by the FCA although we do also recommend products which are not regulated by them.
If things go wrong
If you are ever unhappy with our advice or any aspect of our services, please let us know straight away. We will do our best to resolve your concerns quickly. You can do that by email, letter, or phone. Our contact details are at the end of this document.
We have a complaints guide that is available upon request. If we are not able to resolve your complaint, you may be able to ask the Financial Ombudsman Service to help. The Financial Ombudsman Service settles disputes between financial services businesses and their clients. Whether you have the right to do so depends on exactly what the complaint is about. More information about the Financial Ombudsman Service is available from www.financial-ombudsman.org.uk.
You may also be able to claim compensation from the Financial Services Compensation Scheme if you have suffered a financial loss due to our actions and we are not able to compensate you, perhaps because we have gone out of business. The amount of compensation depends on the work we have done for you and the circumstances of the claim.
You can contact the Financial Services Compensation Scheme or see the link below for more information:
www.fscs.org.uk/what-we-cover/products
Claims about most types of investments are covered for up to a maximum limit of £85,000. Claims about individual securities, including Exchange Traded Funds or Investment Trusts, are usually not eligible for protection at all. Claims about arranging or advising on protection products or insurance is covered for 100% of the claim, with no upper limit. Claims about some pensions and annuities are protected completely, with no upper limit.
Conflicts of interest
We always aim to act in your best interests. However, sometimes we, or one of our other clients, could have an interest in something we are arranging for you. If we are aware of any conflict of interests we will obtain your consent before we carry out your instructions, and explain what we will do to ensure you are treated fairly, although we cannot guarantee that we will be able to identify all situations where there may be a conflict of interest before agreeing to work with you. You should let us know straight away if you become aware of any potential conflicts which could affect our work or service to you, and we will do the same.
Balance: Wealth Planning Limited wholly owns Balance: Trustees Limited which is a non-trading company that can act as a corporate trustee or executor. That relationship does not change our responsibility to provide you with impartial advice. If Balance: Trustees Limited is acting as a trustee or executor for you and Balance: Wealth Planning Limited is also appointed as a financial planner, we will assess whether there is a conflict of interests and provide you with our solution. We have a conflicts of interest policy. If you want to see a copy, please ask us.
Under the rules of our regulator, the FCA, as a firm providing independent advice, we are unable to accept payments or benefits from other firms (such as product providers) as this would conflict with our independent status.
From time to time we may attend training events funded or delivered by product providers, fund managers and investment platforms. These events are designed to enhance our knowledge and enhance the quality of service we provide to our clients. As such this doesn’t affect our obligation to act in your best interests. Please ask us if you want further details.
Protecting your personal information
To provide our services properly, we collect information about your personal and financial circumstances. We take your privacy seriously and will only use your personal information to deliver our services.
Processing your personal data is necessary for us to deliver our contract for services with you. Generally, this is the lawful basis on which we intend to rely for the processing of your data. Our policy is to gather and process only personal data which is necessary for us to conduct our services appropriately with you.
However, there are certain categories of personal data that are sensitive by nature. The categories include data revealing racial or ethnic origin, political opinions, religious or philosophical beliefs, trade union membership and data concerning health. Depending on the nature of the products and services that you engage us for we may need to obtain your sensitive personal data particularly in relation to health. Our policy is that should we require any special category of personal data we will only gather this with your explicit consent and to the detail required.
We adopt a transparent approach to the processing of your personal data. Sometimes we may need to pass your personal information to other organisations. If you apply to take out a financial product or service, we will need to pass certain personal details to the product or service provider.
We may engage the services of third-party providers of professional services, so we can enhance the service we provide to you. These parties may also need to process your personal data in the performance of their contract with us. Your personal information may be transferred electronically (for example by email or over the internet) and we, or any relevant third party, may contact you in future by what we believe to be the most appropriate means of communication at the time (such as phone, email or letter).
The organisations to whom we may pass your details also have their own obligations to deal with your personal information appropriately. Sometimes a product or service may be administered from a country outside Europe. If this is the case, we must put a contract in place to ensure that your information is adequately protected.
As part of our Service Agreement we will ask you to consent to the transfer of sensitive personal information in accordance with the protections outlined above.
We have a detailed Privacy Policy which provides more information about the nature of our personal data processing activities and includes details of your rights of access to the personal information that we hold on you. You can find it here: www.balancewealth.uk/privacy-policy.
If you are concerned about any aspect of our privacy arrangements, please speak to us.
Artificial Intelligence
We use Artificial Intelligence (AI) in some of the work we do. AI is only used in a supportive role (for example, in providing summary meeting notes or checking important information in files). It is not used to generate advice and would never be used as a sole decision maker without human interaction.
AI systems work by learning from the information input and how we require this to be analysed. Any of your personal data that has been processed by AI will not be available to any business or system outside of Balance: Wealth Planning and the AI provider’s secure environment.
Other policies and controls
Communicating with you
We will communicate with you in English, by phone, email, remote meeting or video conferencing tools, and text message unless you ask us not to. We may ask you to confirm your verbal instructions to us in writing, to make sure we are both clear about what is required.
We may record our phone calls or meetings for regulatory purposes and to enable us to listen back to our conversations without needing to write notes at the time. These recordings are for our own internal use and will not be shared with any other party. Copies are available on request.
Best execution
Where we send applications on your behalf to third parties (for example, to make an investment, or make a change to a pension plan) we will take sufficient steps to ensure we obtain the best possible result for you by processing that application accurately and in good time. This is called ‘best execution’. We have a best execution policy. If you want to see a copy, please ask us.
Identification and financial crime
We have controls in place to make sure our business cannot be used for money laundering and other forms of financial crime.
At the start of our working relationship, we will check your identity and ensure that the information we hold is up to date. To do this, we may ask you for original identification documents, or we may use electronic identity verification systems similar to those used for credit checks. We may conduct these checks from time to time throughout our relationship, not just at the beginning. Although these will leave a footprint on your credit records, it will not affect your credit score.
By signing your Service Agreement with us, you give us permission to carry out these checks.
Marketing
We issue email bulletins with news, ideas, updates and invitations to events. These are issued approximately every month. The purpose is to keep you informed and involved. From time to time we may also give you details of additional services which may of interest to you. We do not ever share your details with third parties for marketing purposes.
You may withdraw your consent for us to contact you in this way at any time by notifying us at our main business address, calling 0800 7723456 or emailing us at team@balancewealth.uk.
Changes to our relationship
Amendment
From time to time it may be necessary to amend the terms set out in this document. An up to date copy of this document will always be available on request and on our website. If the change is what we consider to be material and you are engaged as our client, we will send you a copy by email at least 28 days before the new terms take effect.
Any changes to the specific services we provide to you and the associated costs will be covered in a personal Supplemental Service Agreement which we will send to you at least 28 days before the new terms take effect.
Cancellation
We may end our relationship with you at any time, without penalty, and you may do the same. Notice of this termination must be given in writing and will take effect from the date of receipt. Any transactions already started will be completed according to our Service Agreement unless otherwise agreed in writing. You will be liable to pay for any services we have provided before cancellation.